Blog · October 4, 2026
Real Life First: Adapting Your Financial Plan Over Time
Life changes fast. Learn how a financial planner Ottawa families trust helps you adapt your wealth, protection, and legacy plan as your goals shift.
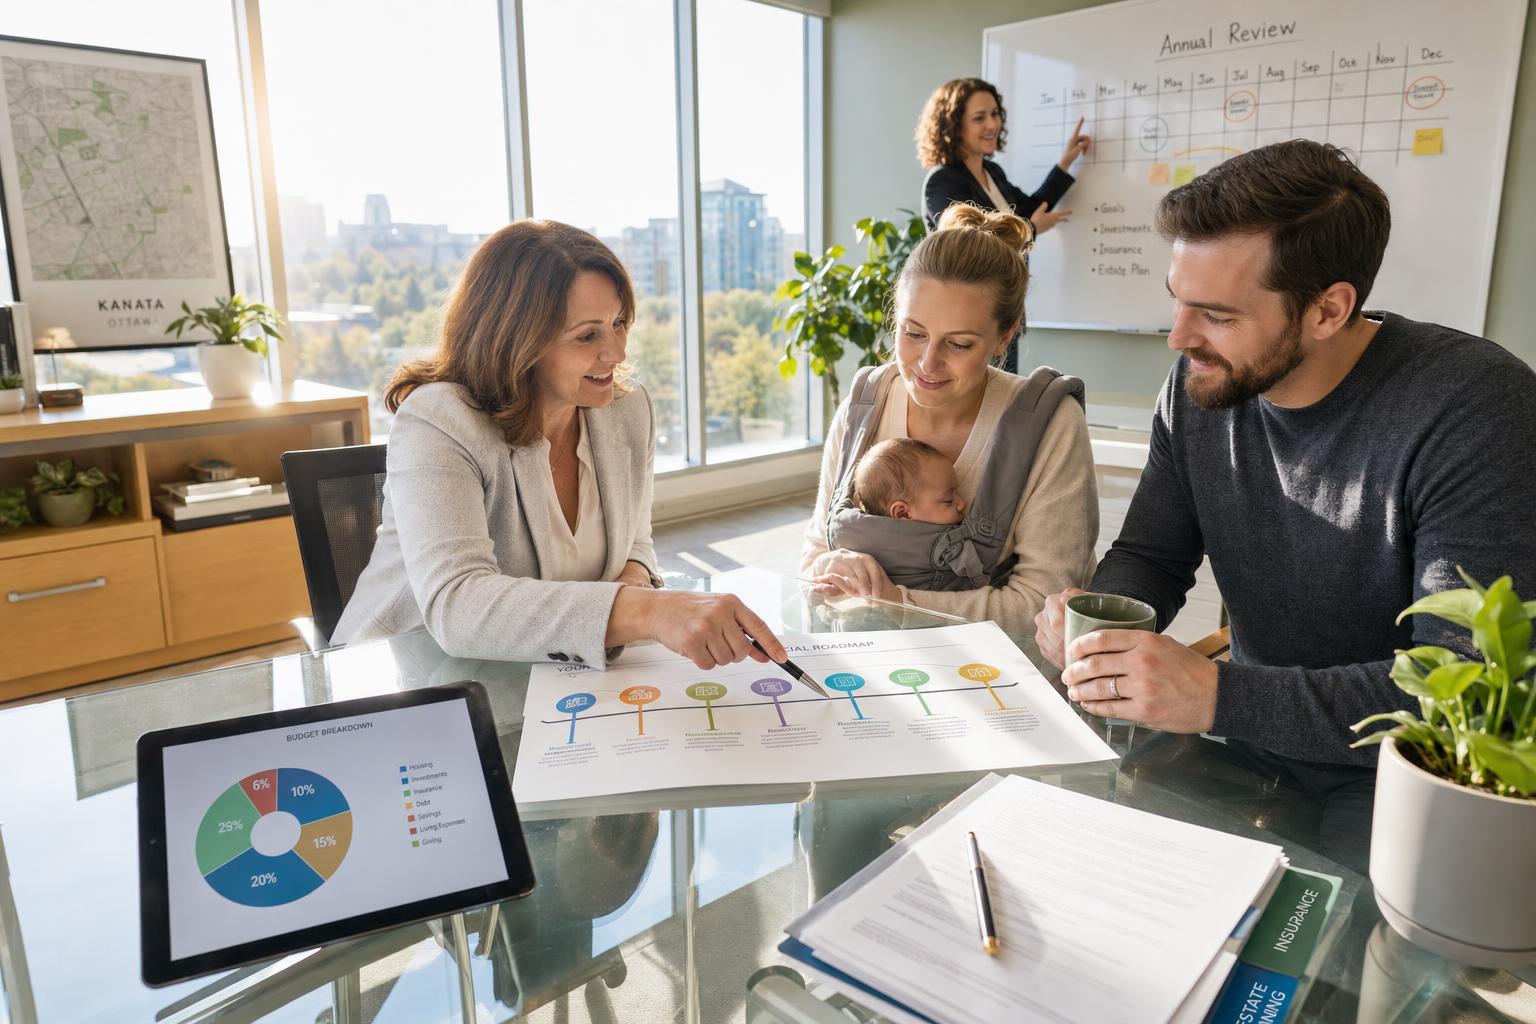
Your financial plan is not a document you sign once and forget. In fact, it is more like a living map that needs updates as your life changes. A good financial planner Ottawa residents rely on will tell you the same thing: real life always comes first, and your plan must bend to fit it.
Marriage, new babies, job changes, business growth, retirement, and even unexpected health events all shift your financial picture. Consequently, a plan built five years ago may no longer serve you today. This guide walks you through how, and when, to adapt your financial strategy so it stays connected to what matters most.
TL;DR: Executive Summary
- Review your plan at least once a year, and always after a major life event such as marriage, a new job, or a home purchase.
- Popular budgeting frameworks like the 70/20/10 rule and 4-3-2-1 rule offer simple starting points, but they should flex as your income and goals change.
- A certified financial planner in Ottawa brings formal training and a fiduciary-style code of ethics, which differs from a general financial advisor title.
- Connecting your wealth, protection, and legacy plans into one strategy prevents gaps that can cost your family time, money, and stress later.
Table of Contents
- Why Financial Goals Need to Be Flexible
- How Often Should I Review My Financial Plan With My Advisor?
- What Life Events Should Trigger a Financial Plan Review?
- What Is the 7-7-7 Rule for Money?
- What Is the 4-3-2-1 Rule in Finance?
- What Is the 70/20/10 Rule for Money?
- How Is a Certified Financial Planner in Ottawa Different From a General Financial Advisor?
- Connecting Wealth, Protection, and Legacy Planning
- Financial Plan Review Checklist
- Frequently Asked Questions
- Key Takeaways
Why Financial Goals Need to Be Flexible
Financial goals need flexibility because life rarely follows a straight line. Incomes rise and fall, families grow, and markets shift. Therefore, a rigid plan often breaks under real-world pressure, while a flexible one adjusts and keeps working.
Think about a plan you made at age 25. Back then, retirement felt distant, and your only goal may have been paying off student debt. By age 40, however, you might own a home in Kanata, run a small business, or support aging parents. Your old plan simply cannot account for all of that.
As a result, flexibility is not a weakness in financial planning. Instead, it is the feature that keeps your plan useful for decades, not just years. A good plan treats your goals as a starting point, not a finish line.
How Often Should I Review My Financial Plan With My Advisor?
Most Canadians should review their financial plan with an advisor at least once a year. However, you should also schedule a review whenever a major life event happens, even if it falls outside your regular check-in schedule.
An annual review allows your financial advisor Ottawa families work with to check your progress against goals. During this meeting, you can discuss investment performance, insurance coverage, tax changes, and any new priorities.
On the other hand, waiting years between reviews can be costly. For example, a client who delays updating beneficiary designations after a divorce may accidentally leave assets to an ex-spouse. Regular reviews catch these gaps before they become real problems.
Suggested Review Frequency by Life Stage
| Life Stage | Suggested Review Frequency | Main Focus Areas |
|---|---|---|
| Early career (20s-30s) | Annually | Debt repayment, emergency fund, early investing |
| Growing family (30s-40s) | Annually, plus after major events | Insurance, education savings, home ownership |
| Peak earning years (40s-50s) | Annually | Retirement savings, business succession, tax planning |
| Pre-retirement (50s-60s) | Every 6 to 12 months | Pension income, estate planning, healthcare costs |
| Retirement | Annually, plus after health changes | Income drawdown, legacy planning, long-term care |
What Life Events Should Trigger a Financial Plan Review?
Major life events that should trigger a financial plan review include marriage, divorce, a new baby, a job change, a business sale, or the death of a loved one. Each of these shifts your cash flow, risk, or long-term goals.
Specifically, here are common triggers worth watching for:
- Marriage or common-law partnership: You may need to combine finances, update wills, and adjust insurance beneficiaries.
- New child or dependent: Education savings plans and life insurance needs often increase.
- Job loss or career change: Your cash flow and benefits coverage may shift suddenly.
- Buying or selling a home: Mortgage terms, insurance, and debt ratios all change.
- Starting or selling a business: Tax structure and succession planning become urgent.
- Divorce or separation: Asset division and updated estate documents are essential.
- Retirement approaching: Income strategy shifts from saving to drawing down assets.
- Health diagnosis: Insurance coverage and estate plans may need urgent updates.
If you own property or work in real estate, changes to your portfolio can also trigger a review. For example, professionals exploring options can look into financial planning for real estate professionals to see how property income affects a broader plan.
What Is the 7-7-7 Rule for Money?
The 7-7-7 rule for money is a simple guideline some planners use for spending reflection. It suggests waiting 7 minutes, 7 hours, or 7 days before making a purchase, depending on its size, to avoid impulse spending.
For small purchases, a 7-minute pause may be enough. For mid-size purchases, waiting 7 hours allows emotions to settle. For larger purchases, such as a vehicle or vacation, a full 7-day wait gives you time to compare options and confirm the purchase fits your budget.
This rule is not a strict law of finance. Instead, think of it as a practical habit that protects your long-term goals from short-term impulses. Over time, this small pause can prevent thousands of dollars in unplanned spending.
What Is the 4-3-2-1 Rule in Finance?
The 4-3-2-1 rule in finance is a budgeting guideline that suggests spending 40 percent of income on living costs, saving 30 percent for a home or large goals, putting 20 percent into long-term investments, and using 10 percent for giving or discretionary spending.
This framework works well for people with stable, moderate incomes. However, it may not fit everyone. For instance, a small business owner with variable income may need a more flexible split that adjusts month to month.
Therefore, treat the 4-3-2-1 rule as a starting template, not a fixed formula. Your Ottawa-based advisor can help you adjust the percentages based on your actual debt load, family size, and savings goals.
What Is the 70/20/10 Rule for Money?
The 70/20/10 rule for money suggests spending 70 percent of income on needs and daily expenses, saving 20 percent, and putting 10 percent toward debt repayment or giving. It is one of the simplest budgeting frameworks available.
This rule works particularly well for beginners who feel overwhelmed by detailed budgeting categories. Since it only has three buckets, it is easy to track using a basic spreadsheet or banking app.
Still, as your income grows, this ratio may shift. For example, higher earners often save more than 20 percent, since their basic needs take up a smaller share of their total income.
How Is a Certified Financial Planner in Ottawa Different From a General Financial Advisor?
A certified financial planner in Ottawa holds the CFP designation, which requires formal education, a board exam, and ongoing ethics standards. A general financial advisor, on the other hand, may sell specific products without the same breadth of training.
In Canada, the CFP designation is overseen by FP Canada. To earn it, a planner must complete accredited coursework, pass a national exam, and commit to continuing education every year. As a result, a certified financial planner Ottawa clients choose typically offers a more holistic view of your finances, covering tax, retirement, insurance, and estate planning together.
A general advisor may still be well qualified, especially for specific products like mutual funds or insurance policies. However, if you want one person coordinating your entire financial picture, a CFP is often the stronger choice.
Certified Financial Planner vs Financial Advisor Ottawa
| Feature | Certified Financial Planner (CFP) | General Financial Advisor |
|---|---|---|
| Education requirement | Accredited coursework plus national exam | Varies by role and licence type |
| Scope of advice | Holistic: tax, retirement, estate, insurance | Often product-specific |
| Ethics oversight | FP Canada code of ethics | Depends on licensing body |
| Best suited for | Complex, long-term planning needs | Single-product needs (e.g., one policy) |
Connecting Wealth, Protection, and Legacy Planning
Many Canadians build their wealth, insurance, and estate plans in separate silos. Unfortunately, this approach often leaves gaps. A missed beneficiary update or an outdated will can undo years of careful saving.
When we worked with a small business owner in Ottawa who was preparing to sell her company, we saw how disconnected planning almost cost her family significant tax savings. Her investment plan was strong, but her estate documents had not been updated in over a decade. By aligning her wealth strategy with updated estate planning and insurance coverage, we helped her protect both her business proceeds and her family's future.
This is the core idea behind connected planning. Your wealth management strategy should always talk to your protection plan, which includes insurance such as life, disability, and critical illness coverage. In turn, both should feed directly into your estate and legacy planning Ottawa families rely on to pass on assets smoothly.
For families who are newcomers to Canada or new homeowners, this connection matters even more. You can explore how this works through financial planning for families, newcomers, and homeowners, which addresses these unique transition points.
Practical Example: The Three-Plan CheckBefore any major decision, such as buying a home or selling a business, ask yourself these three questions:
- Does my wealth plan still match my current income and goals?
- Does my protection plan (insurance) cover my current family size and debts?
- Does my legacy plan (will, beneficiaries, trusts) reflect my current wishes?
If you answer "no" or "not sure" to any of these, it is time to book a review with your planner.
Financial Plan Review Checklist
Use this checklist before your next meeting with your financial planner Ottawa trusts for wealth and legacy planning. It will help you organize your thoughts and make the most of your session.
- Gather recent pay stubs, tax returns, and investment statements.
- List any life changes since your last review (marriage, new job, new child, etc.).
- Check beneficiary designations on insurance policies and retirement accounts.
- Review your will and power of attorney documents for accuracy.
- Confirm your insurance coverage still matches your debts and dependents.
- Revisit your retirement timeline and savings targets.
- Discuss any new business income, side ventures, or rental properties.
- Set one or two updated goals for the next 12 months.
Small business owners and incorporated professionals often have extra layers to review, such as corporate structure and succession planning. If this applies to you, a resource like financial planning for business owners can offer more specific guidance.
Frequently Asked Questions
Why do I need to adapt my financial plan instead of just setting it once?
Life changes constantly, and a static plan cannot keep up with new goals, incomes, or family situations. Therefore, regular updates keep your plan useful and accurate over time.
Can I use more than one budgeting rule at the same time?
Yes, you can blend ideas from the 70/20/10 rule, the 4-3-2-1 rule, and the 7-7-7 rule. In fact, many Ottawa households mix frameworks to fit their unique income and goals.
Do I need a certified financial planner if I already have an insurance advisor?
Not always, but a certified financial planner can help connect your insurance coverage with your broader wealth and estate goals. This coordination often prevents costly gaps.
How much does it cost to work with a financial planner in Ottawa?
Costs vary depending on the planner's fee structure, which may include flat fees, hourly rates, or a percentage of assets managed. It is best to ask directly during an initial consultation.
What happens if I skip my annual financial review?
Skipping a review will not cause immediate harm. However, over several years, outdated plans can lead to missed tax savings, wrong beneficiaries, or insufficient insurance coverage.
Key Takeaways
- Review your financial plan at least once a year, and immediately after major life events.
- Budgeting frameworks like 70/20/10 and 4-3-2-1 are helpful starting points, not rigid rules.
- The 7-7-7 rule can curb impulse spending through simple waiting periods.
- A certified financial planner in Ottawa brings broader training than many general advisors.
- Wealth, protection, and legacy plans work best when they are connected, not separate.
- Use a simple checklist before every review to stay organized and proactive.
Conclusion: Keep Real Life at the Center of Your Plan
Your financial plan should always serve your real life, not the other way around. As your goals shift, your strategy needs to shift with them. Consequently, regular reviews with a trusted professional keep your wealth, protection, and legacy plans working together, not against each other.
If it has been more than a year since your last review, now is a good time to start. Reach out to a qualified financial planner Ottawa families and business owners trust, and build a plan that truly keeps pace with your life.