Business Insurance · Ottawa

Business insurance shaped around your daily work.

A customer injury, damaged equipment or unexpected shutdown can affect more than the day’s income. Compare protection for the work you do, the assets you use and the responsibilities you take on.

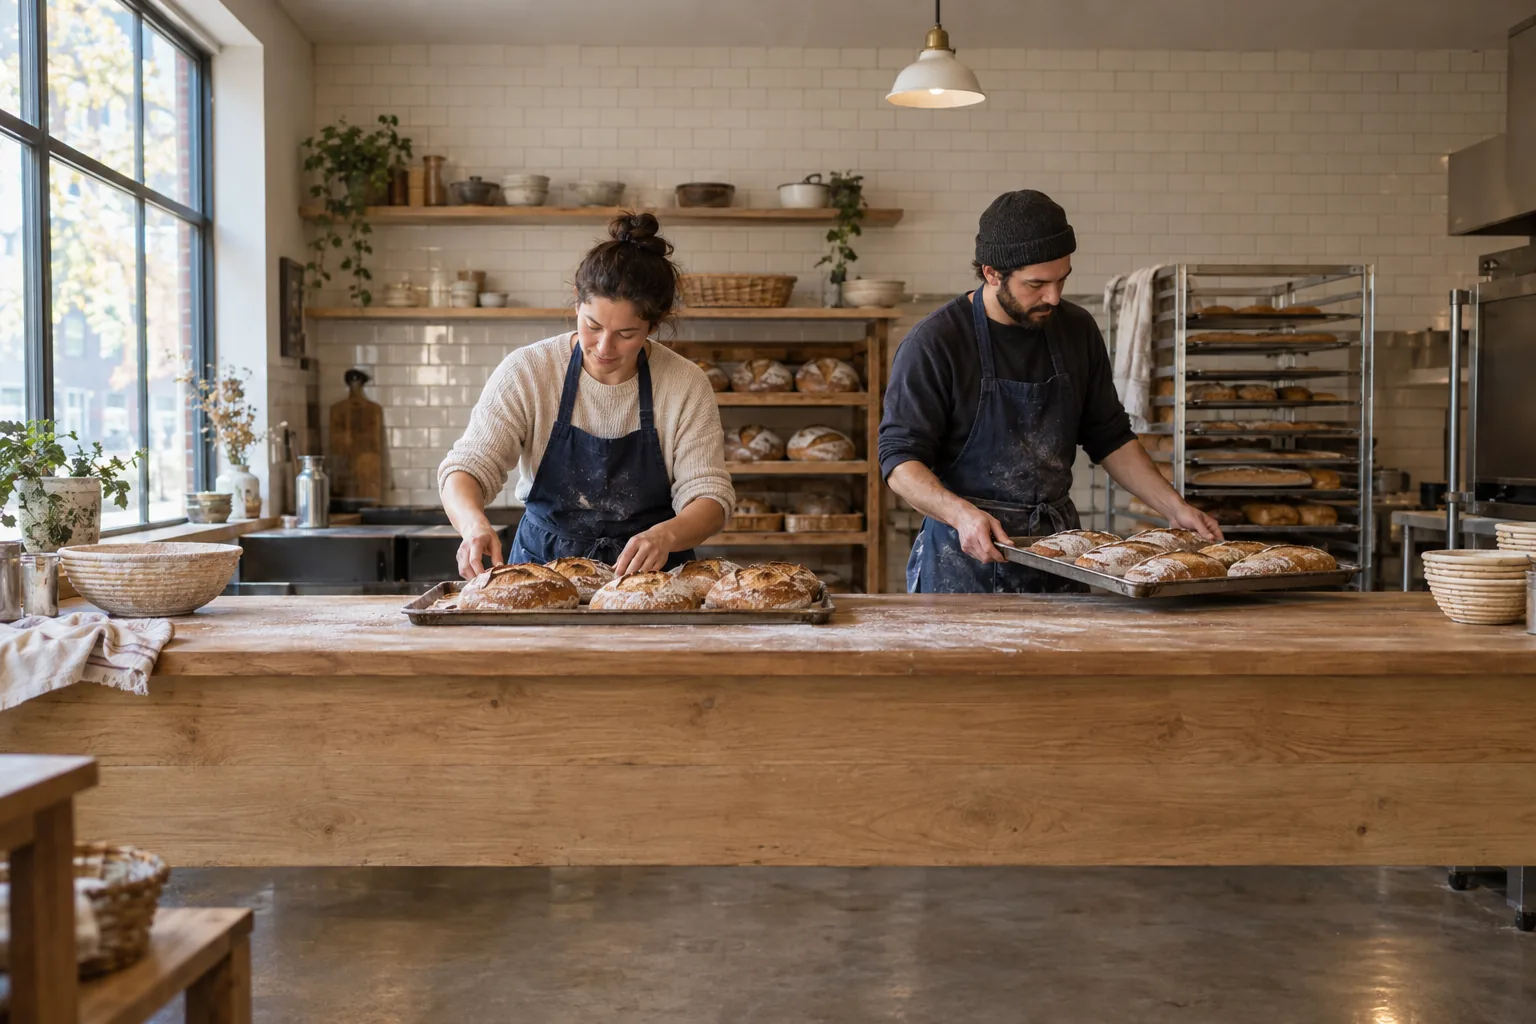
An independent bakery owner and colleague preparing bread before opening

Build around your operation

Which risks does your business need to cover?

Available protection depends on your activities, industry and eligibility. A package may combine coverages; it does not automatically include every risk.

Liability and professional work

Commercial general liability
May respond to eligible injury or property-damage claims involving your operations, products or premises.
Professional liability
Also called errors and omissions insurance. May respond to eligible claims involving professional errors, negligence or failure to provide contracted services.
Product liability
May address eligible injury or property-damage claims involving products you manufacture, distribute or sell.

Assets and business income

Tools and equipment
May cover eligible tools and portable equipment at job sites or in transit.
Commercial property
May protect eligible buildings, inventory, equipment and contents.Explore commercial property
Business interruption
May replace eligible lost income and continuing expenses after a covered loss disrupts operations. It does not cover every cause of shutdown.

Digital risks, crime and vehicles

Cyber insurance
May cover selected forensic, notification, recovery, legal or interruption costs following an eligible cyber incident. Traditional policies may offer little or no cyber protection.
Commercial crime
May address selected losses from employee dishonesty, fraud, forgery or theft.
Commercial auto
May cover vehicles used for eligible business purposes. Personal auto cover may not fit deliveries or other commercial use.

Before you choose a policy

Check the gaps behind the quote.

Compare premiums and deductibles with the losses the business can afford to absorb.

A hand plane and measuring tools beside an unfinished cabinet joint on a workbench
  1. Operations and contracts

    Disclose every service, product, activity and territory. Check limits, exclusions, additional-insured requirements and proof of insurance against customer, landlord and lender contracts.

  2. Claims and legal costs

    Check occurrence versus claims-made wording, retroactive dates, reporting requirements and continuity of cover. Confirm whether defence costs sit within the limit or are paid in addition.

  3. Property and recovery

    Compare replacement cost with depreciated value, keep asset limits current, and check how long interruption benefits last. Revenue may recover later than the premises.

  4. Changes in the business

    Report new activities, vehicles and locations, including moves, renovations, subletting or vacancy. Confirm cyber protection and whether vehicles need commercial cover or an endorsement.

Consider the details of your industry.

Contractors and Trades
  • Damage at a job site
  • Tools and mobile equipment
  • Completed operations
  • Subcontractors
  • Commercial vehicles
  • Installation errors
  • Contractual insurance requirements
Consultants and Professional Practices
  • Professional negligence
  • Errors and omissions
  • Privacy obligations
  • Cyber incidents
  • Client contracts
  • Lost documents or data
Retailers and Wholesalers
  • Customer injuries
  • Product liability
  • Inventory loss
  • Crime
  • Equipment breakdown
  • Business interruption
Restaurants and Hospitality Businesses
  • Food-related liability
  • Equipment breakdown
  • Fire
  • Spoilage
  • Customer injuries
  • Liquor-related liability, where applicable
Technology and Online Businesses
  • Data breaches
  • Cyber extortion
  • Technology failure
  • Professional errors
  • Privacy claims
  • Media and intellectual-property allegations
Home-Based Businesses

A personal home policy may provide little or no protection for:

  • Business equipment
  • Customer visits
  • Professional liability
  • Inventory
  • Off-premises tools
  • Business interruption

Operating from home should be disclosed to the home insurer.

Business insurance FAQ

Questions about your responsibilities.

Is business insurance legally required?

Requirements depend on the business, industry, location and activities. Landlords, lenders, customers, professional bodies and government contracts may also require specified coverage.

Does incorporating protect me from every liability?

No. Incorporation may provide some legal separation, but it does not eliminate every personal, professional, contractual or operational exposure.

Do independent contractors need their own insurance?

Often, yes. Require appropriate proof of coverage and review contractual responsibilities with qualified legal and insurance professionals.

Their policy may not automatically protect your company. Review certificates, limits and responsibilities.

Does my home policy cover my home-based business?

It may provide little or no business protection. Notify the home insurer and explore appropriate business coverage.

Centerpointe Financials advisor

Review with Centerpointe

Bring your current policy and business plans.

We’ll discuss your operations, revenue, employees, customers, property and contracts, review existing coverage, and compare suitable options.

Review your cover as services, products, staff, contracts, equipment, locations or revenue change.

Planning for owners and key people?

Corporate insurance addresses ownership, key people, buy-sell obligations, succession and continuity after death or disability, including corporate-owned life insurance and estate or legacy needs. A company may need both operational and ownership protection.

Explore corporate insurance

Business Insurance Areas We Serve

Business insurance guidance in Ottawa and neighbouring Eastern Ontario communities.

View all areas we serve

Business insurance products are subject to application, underwriting, eligibility, policy terms and insurer approval.

Covered operations, limits, deductibles, exclusions, endorsements, settlement terms, business-interruption periods, reporting requirements and premiums vary by policy, industry and insurer.

Not every business activity, contract, professional service, cyber event, vehicle, worker, property or cause of interruption is covered. Material changes in operations must be disclosed to the insurer.

Legal agreements, regulatory obligations and tax matters should be reviewed by appropriately qualified professionals.