Commercial Property Insurance · Ottawa

Protect what it takes to rebuild and reopen.

Your premises, equipment and stock keep the business working. Commercial property insurance can protect eligible physical assets; selected business-interruption coverage can help with income lost after a covered event.

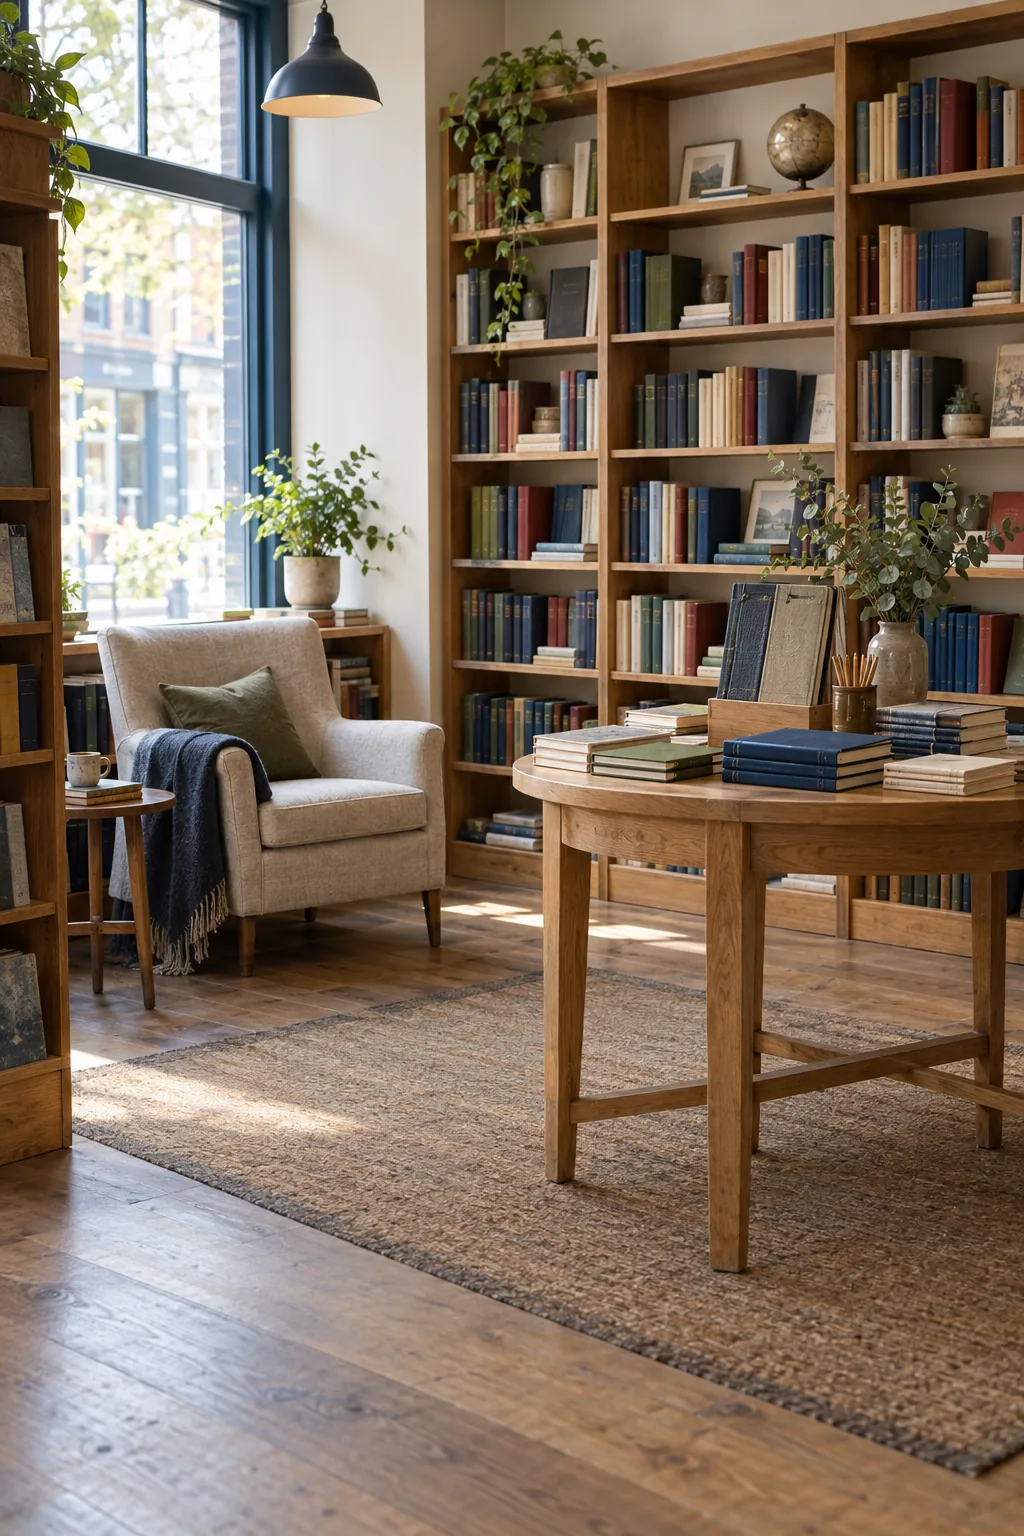
Bookshelves, display tables and a reading chair inside an independent bookshop

Start with the assets

Cover the building and what happens inside it.

Premises and improvements

Owned buildings, permanent fixtures and tenant improvements may be covered. Signs, landscaping and other outdoor property have their own limitations. Check your lease: the landlord’s policy does not automatically protect a tenant’s interests.

Contents, stock and equipment

Review furniture, computers, machinery, raw materials and goods for sale. Allow for seasonal stock changes. Tools, mobile equipment and goods in transit may need separate off-premises coverage.

Property and recovery costs

Customer, leased or borrowed property must be specifically covered. Policies may include eligible record-recreation and debris-removal expenses. Check whether rebuilding to current codes needs additional cover.

Retail, hospitality, professional practices and warehouses have different exposures. Disclose vacancy, renovations, new tenants, construction work and changes in how the premises are used.

Review the claim response

A policy limit is only part of the recovery plan.

Compare the insured events, valuation method and recovery period. A low premium is less useful if the policy excludes the loss that stops your business.

Which causes of damage are covered?

Fire, smoke, theft, vandalism, wind, hail and some water damage may be covered under the contract. Water escape, sewer backup, overland flood and groundwater are treated differently. Flood, earthquake and equipment breakdown may require additions.

Wear, poor maintenance, pollution and cyber incidents may be excluded or need specialized protection. Temperature-sensitive or valuable stock also needs specific review.

How will damaged property be valued?

Replacement-cost and actual-cash-value settlements differ. The latter generally allows for depreciation. Check current rebuild and equipment costs, deductibles, sublimits, any agreed-value arrangement and peak-season stock protection.

How long could income support continue?

Business interruption is not automatically included. After an eligible insured event, selected cover may address lost income, continuing expenses, specified payroll, relocation or rental income. Check the trigger, waiting period, indemnity period, supplier dependencies and required records.

Estimate time for permits, construction and replacement equipment. This coverage does not protect against every revenue decline or business closure.

Questions before you decide

Look closely at the details.

Is commercial property insurance legally required?

Requirements depend on the business and property. Lenders, landlords, leases, contracts and other parties may require specified coverage and limits.

Is market value the right amount to insure?

Not necessarily. Market value includes land and location, while property insurance limits often need to reflect reconstruction or replacement costs.

What is co-insurance?

Co-insurance is a policy condition requiring property to be insured to a specified proportion of its value. Failing to meet the requirement may reduce an eligible claim payment.

Centerpointe Financials advisor

Review with Centerpointe

Bring the property details and current policy.

We’ll review occupancy, construction, fire protection, asset values and the time needed to recover. Revisit the limits after renovations, equipment purchases, inventory growth, inflation, changes in occupancy or expansion.

Commercial Property Insurance Areas We Serve

Commercial Property Insurance guidance in Ottawa and neighbouring Eastern Ontario communities.

View all areas we serve

Commercial property and business-interruption insurance products are subject to application, underwriting, inspection where applicable, eligibility, policy terms and insurer approval.

Covered property, causes of loss, valuation methods, limits, co-insurance requirements, deductibles, exclusions, endorsements, waiting periods, indemnity periods and premiums vary by policy, property and insurer.

Not every water event, natural hazard, equipment failure, cyber incident, vacancy, renovation, mobile asset or interruption is covered. Material changes involving property, occupancy and business operations must be disclosed.

Website information is general and does not constitute individualized insurance, legal, construction, valuation, accounting or tax advice.