
Life Insurance for Young Families · Ottawa

Protect the Life Your Family Is Building

Life insurance can help your family meet everyday costs and protect future plans if a parent dies. We help young families in Ottawa find coverage that fits their responsibilities and budget.

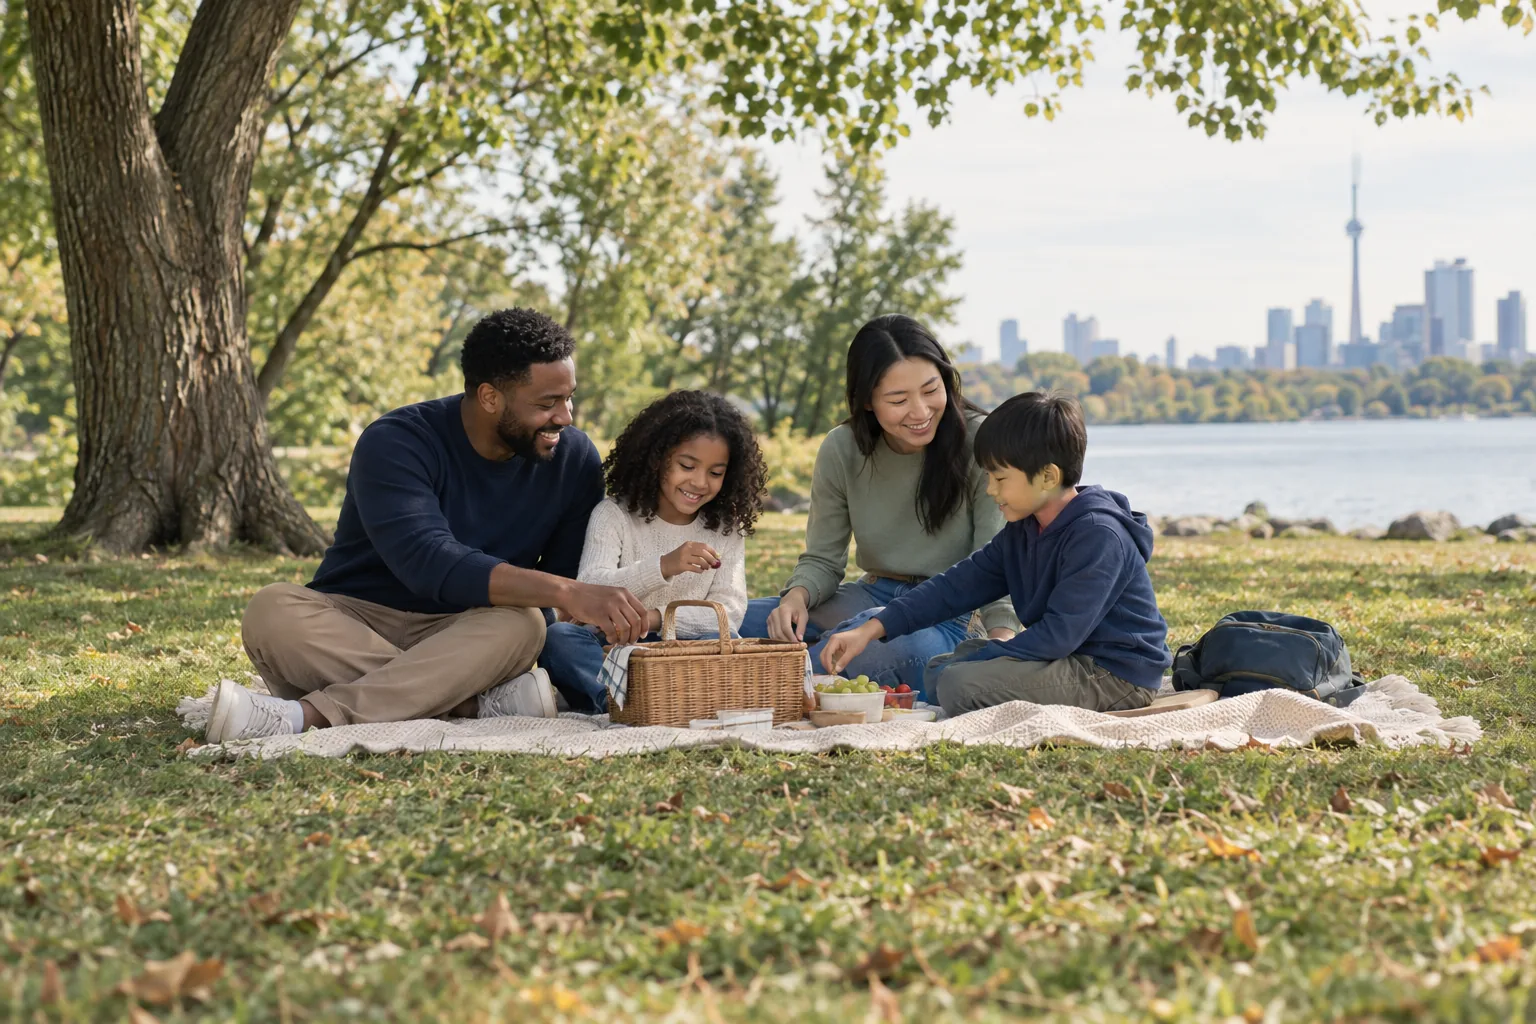
Parents and two young children sharing a simple picnic in a leafy park

Start with what your family needs

What would your coverage need to replace?

Children’s drawings, a toy horse and a backpack on a wooden shelf

Consider both parents. Unpaid childcare and household support can be costly to replace, even when one parent earns most of the income.

A useful estimate weighs your family’s responsibilities against the resources already available.

  • Income & everyday costs

    The income your household would need, and for how long.

  • Home & debts

    Mortgage or rent, loans and other outstanding obligations.

  • Care & household support

    Childcare, transportation and unpaid work that would need replacing.

  • Education & immediate needs

    Children’s future plans, final expenses and time for the family to adjust.

  • Resources already in place

    Savings, investments, workplace benefits and current policies.

  • Budget & coverage period

    Premiums you can maintain for as long as the need continues.

Estimate your protection gap

The calculator gives an estimate. A personalized review is needed before choosing coverage.

Choose the coverage period

Protection for now, or for life.

Life insurance provides a death benefit to the named beneficiary or beneficiaries when the insured person dies while the policy is in force and the claim requirements are satisfied.

A defined period

Term life insurance

Term insurance provides protection for a defined period. It may be appropriate while your children are dependent, your mortgage is outstanding or your family relies heavily on your income.

It generally begins with a lower premium than permanent insurance for the same initial coverage amount. Premiums may increase if the policy renews after its original term.

Explore Term Life Insurance

Lifelong needs

Permanent life insurance

Permanent insurance is designed to provide lifelong coverage when the policy requirements are met. Depending on the product, it may also accumulate cash value.

It may be considered for lifelong dependants, final expenses, estate objectives or a legacy for the next generation.

Explore Permanent & Whole Life

Some families combine both types to address temporary and lifelong needs.

What to expect

A straightforward family review.

  1. Tell us about your family

    Bring your priorities and any existing policy details. We’ll review what your family depends on.

  2. Compare your options

    We explain the protection gap, coverage periods and available policy choices.

  3. Apply when you’re ready

    We support the application and underwriting, then help keep coverage current as life changes.

A few more questions

Before you choose a policy.

Is the life insurance provided by my employer enough?

It may provide useful protection, but the benefit could be limited or connected to your employment. Compare the amount with your family’s complete financial needs and confirm what happens if you change jobs.

Should we buy mortgage insurance or personal life insurance?

Mortgage life insurance is generally designed to address the lender’s outstanding balance, while personally owned life insurance pays the benefit to your named beneficiaries. Coverage, underwriting and portability differ, so compare the policy terms rather than choosing based only on convenience.

Can a stay-at-home parent qualify for coverage?

A stay-at-home parent may qualify, subject to the insurer’s underwriting and financial guidelines. The amount should reflect the financial cost of replacing their childcare and household responsibilities.

Who should we name as beneficiary?

A spouse or partner is often named, but the appropriate choice depends on your family and estate plan. Naming a minor child directly can create legal and administrative complications, so obtain legal advice before deciding.

Do we need medical examinations?

Not every application requires an examination. The insurer may use health questions, prescription information, telephone interviews, medical records or testing as part of underwriting.

When should we review our coverage?

Review it after the birth or adoption of a child, a home purchase, marriage, separation, employment change, income increase, major debt or other significant family event.

Your next step

Let’s look at your family’s plan.

Bring your questions and any existing policy details to a complimentary review with our Ottawa team.

Make room for the conversation.

Life Insurance for Young Families Areas We Serve

Family insurance guidance in Ottawa and neighbouring Eastern Ontario communities.

View all areas we serve

This page provides general educational information and does not constitute insurance, investment, legal, accounting or tax advice.

Life insurance is subject to eligibility, underwriting, exclusions, limitations, premiums and approval by the issuing insurer. Coverage takes effect only when confirmed according to the insurer’s requirements. The issued policy contract governs all benefits and obligations.

Premiums, renewal provisions, conversion options, cash values and guarantees vary by policy. Do not cancel existing insurance until replacement coverage has been approved, issued and accepted.

Beneficiary and estate-planning decisions may have legal and tax consequences. Obtain qualified legal and tax advice where appropriate.