Group Benefits · Ottawa

Benefits your people can use, at a cost you can plan for.

Build a benefits plan around your workforce and budget. We help eligible Ottawa businesses compare coverage, understand the costs and prepare for enrolment and renewal.

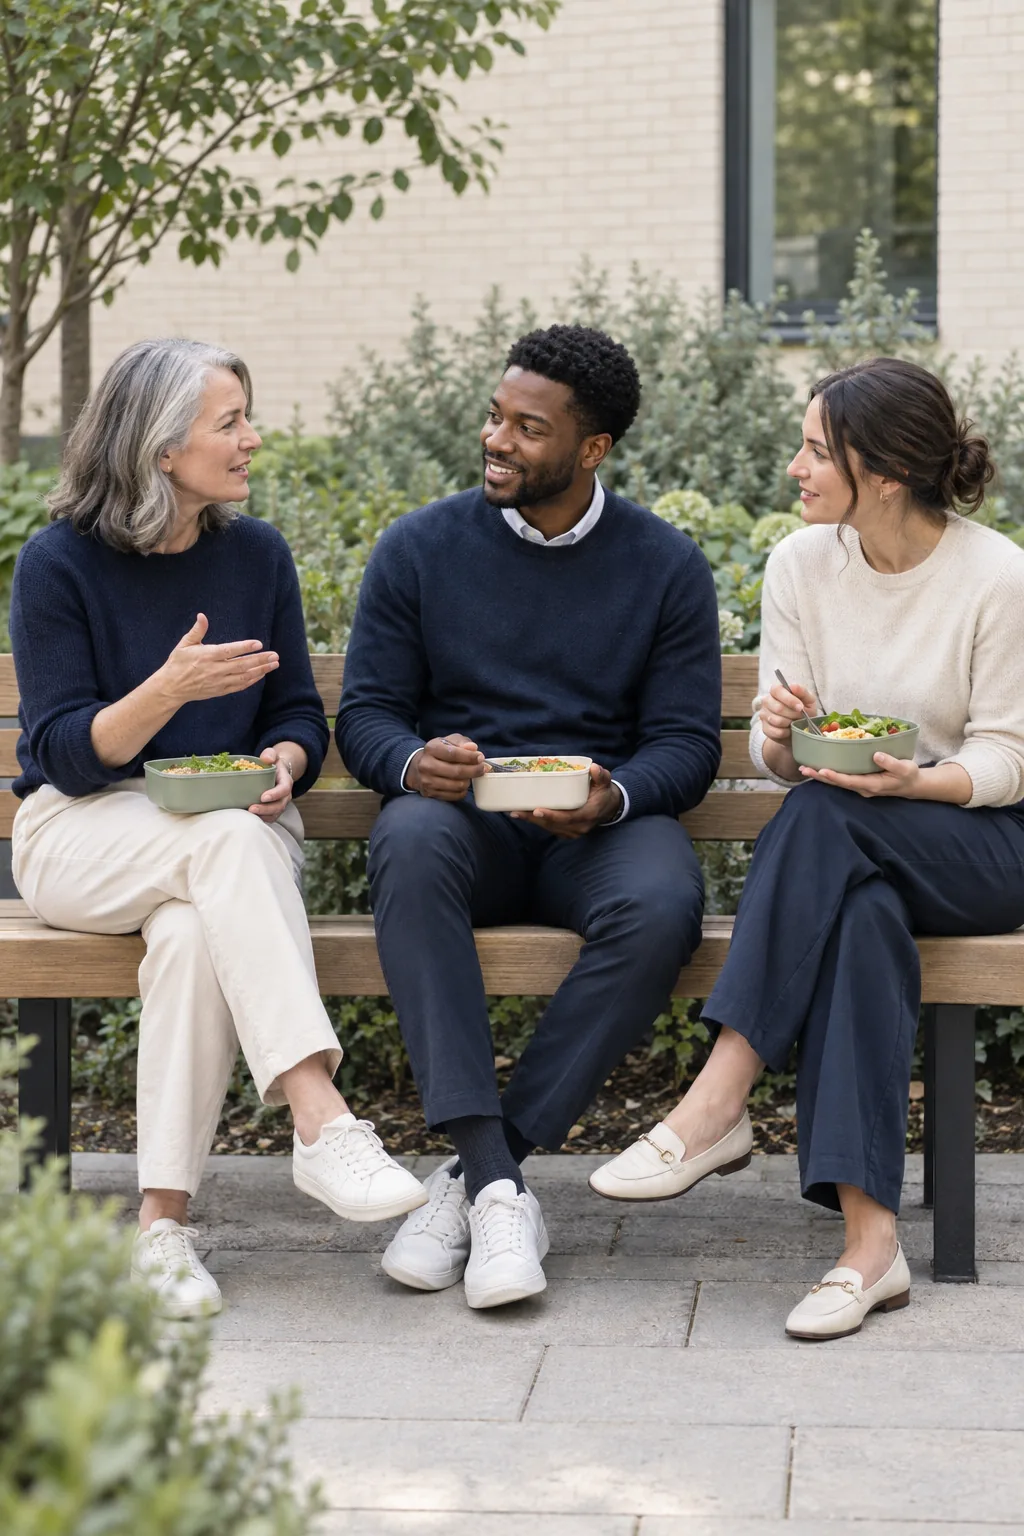
Colleagues of different ages sharing a break outside a small workplace

Choose the benefits that fit

Everyday care and protection for larger risks.

Availability depends on the provider, group size and plan design. Compare the coverage definitions and limits as well as the premium.

Health and dental

Eligible drugs, practitioners, vision, medical supplies and dental treatment may be reimbursed. Travel medical, hospital and orthodontic benefits depend on the plan. Deductibles, reimbursement limits, fee guides and waiting periods can apply.

Life and accident protection

Group life may pay a death benefit for eligible employees. Accidental death and dismemberment coverage provides specified benefits for eligible accidents and covered losses.

Disability income

Short-term and long-term disability benefits may replace part of eligible income. Waiting periods, benefit duration and the plan’s definition of disability determine when support is payable.

Critical illness

A lump-sum benefit may be payable after an eligible diagnosis that meets the policy definition and claim requirements.

Assistance and virtual care

Some plans offer confidential counselling, referrals or family assistance, alongside eligible virtual healthcare services.

Health care spending account

A defined allowance reimburses eligible medical and dental expenses under plan and tax rules. It may complement insurance, but a capped account does not transfer larger risks in the same way.

Products, coverage, limits, participation requirements and eligibility vary by provider and group.

Design for the long term

Balance coverage with the cost of keeping it.

Start with what employees need and what the business can sustain. Cost reductions can move expenses or risk to employees, so compare their effect as well as the immediate saving.

Set eligibility and participation rules

Define eligible employees by objective criteria such as employment status, hours or length of service. Agree on waiting periods, dependant coverage and participation requirements with the provider. Legitimate employee classes may have different benefits, subject to provider acceptance, applicable rules and consistent administration.

Choose coverage levels and cost-sharing

Decide how the employer and employees will share premiums. Compare deductibles, reimbursement percentages, annual maximums and benefit amounts. Spending accounts or flexible options may add choice, subject to provider availability and tax treatment.

Understand renewal costs before changing the plan

Pricing may reflect claims, group size, demographics, occupations, participation and healthcare inflation. Review benefit limits, contributions, drug formularies, high-cost drug provisions and provider options. Consider employee education and administration as well as price.

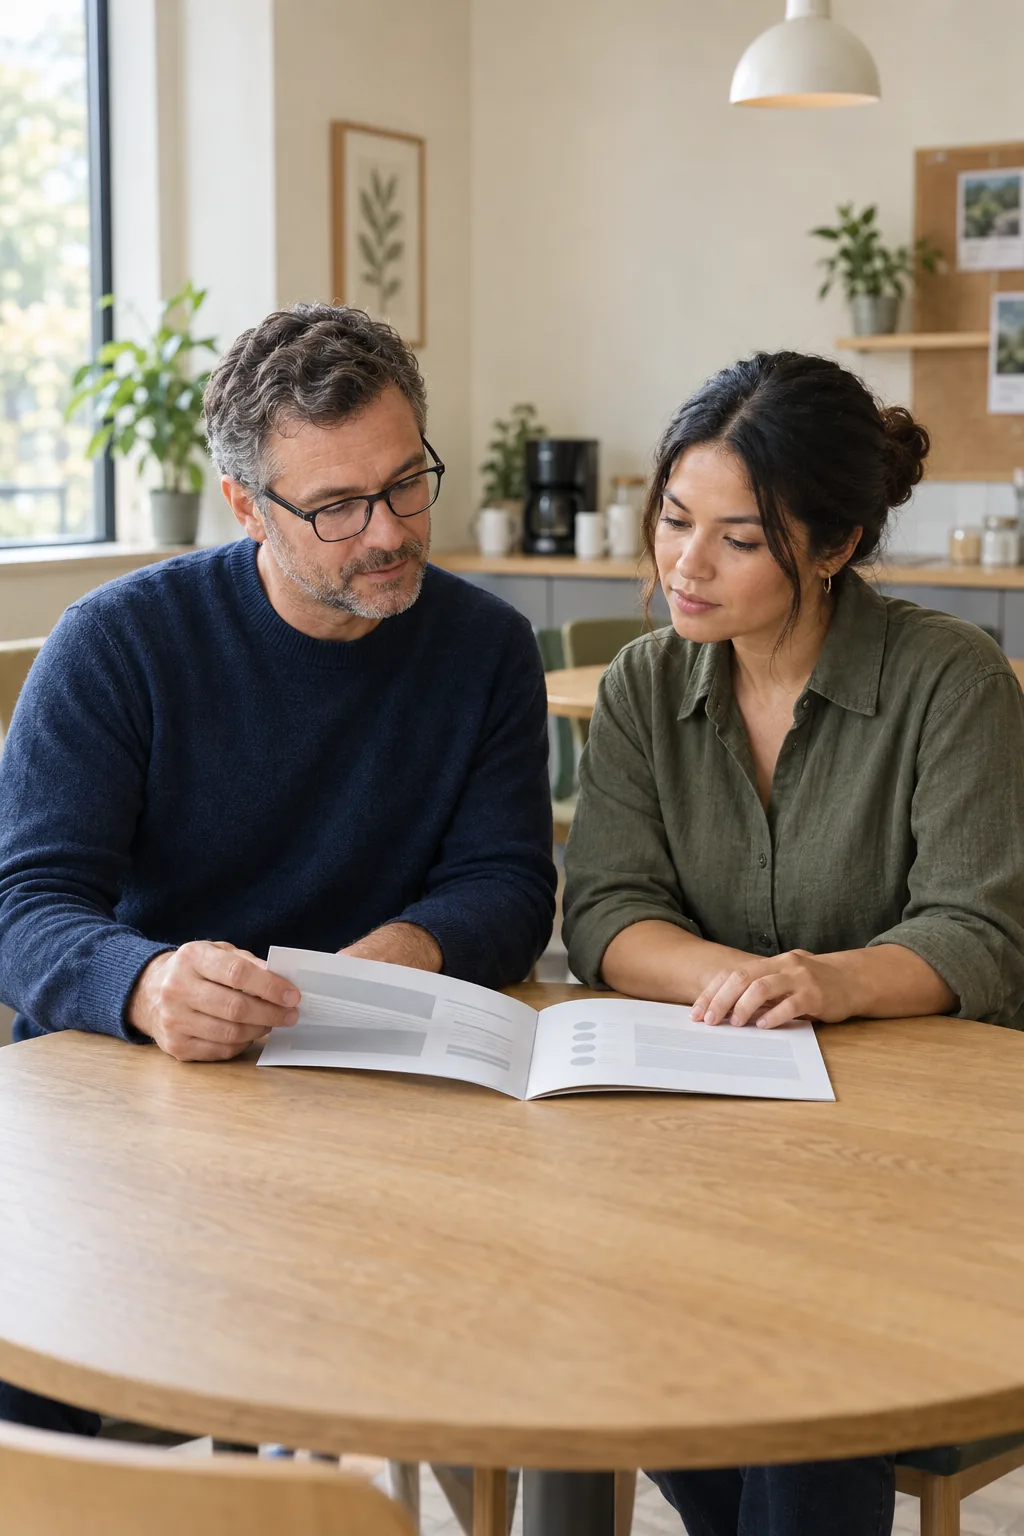
A small-business owner and employee discussing a benefits booklet

Make the plan easy to use

Clear enrolment. Fewer unanswered questions.

Give employees a simple explanation of when coverage begins, how to enrol and claim, and where to check limits, pre-authorizations and confidential support. Explain coordination with a spouse’s plan and what happens during leave.

Keep salary, dependant and employment records current, protect personal information and communicate changes promptly. Late administration can affect eligibility, premiums or claims.

Explain what happens when employment ends

Group coverage generally ends under the plan terms. Some benefits may offer conversion or continuation within strict deadlines. Personal insurance can help address needs that continue beyond employment; review the options before coverage ends.

Explore personal health and dental coverage

Questions before you decide

Look closely at the details.

How many employees are required for a group plan?

Minimum participation and group-size requirements vary by provider, product and plan structure. Some solutions may be available for very small eligible groups.

Can employees decline coverage?

Provider rules vary. Employees may be able to waive health or dental benefits if they have acceptable comparable coverage elsewhere, but other benefits may remain mandatory.

Are employer-paid benefits taxable to employees?

It depends on the benefit, funding arrangement and jurisdiction. Health and dental benefits under a qualifying private health services plan may receive different treatment from group life or disability premiums. Obtain current payroll and tax advice.

Can we change providers?

Potentially. Compare pricing, coverage definitions, transition rules, ongoing claims, disability provisions, administration and employee disruption before moving.

Centerpointe Financials advisor

Review with Centerpointe

Bring your workforce priorities and current plan.

We’ll review the employee group, budget, benefits and provider terms, then compare suitable options and help explain enrolment responsibilities. Review the plan at renewal and after major changes in the workforce, budget or business objectives.

Group Benefits Areas We Serve

Group Benefits guidance in Ottawa and neighbouring Eastern Ontario communities.

View all areas we serve

Group insurance and benefits products are subject to application, underwriting where applicable, group eligibility, minimum participation, policy terms and provider approval.

Benefits, employee classes, deductibles, reimbursement percentages, maximums, exclusions, waiting periods, conversion options, premiums and renewal terms vary by plan and provider.

Tax treatment depends on the benefit, funding arrangement, employee contributions, jurisdiction and current tax law. Centerpointe Financials does not provide legal, employment, payroll, accounting or tax advice.

Employers should obtain advice from appropriately qualified professionals regarding employment standards, human rights, privacy, taxation and plan governance.